
Most buyers arrive at one of two moments: the very beginning, or with a house already in mind. Both are the right time to talk — what changes is where we start.
You have never done this and the internet has been unhelpful. We start with the number that actually matters — what you need saved, including closing costs, not just the down payment — and walk through which programs you qualify for. No pressure to apply on the first call.
You have owned before, and this time there is equity, a sale to coordinate, or a deadline. We look at how your current home fits into the purchase, what your timeline allows, and which program leaves you the most room at closing.
Two buyers can pay the same price for the same house and end up with very different monthly payments, because the loan program decides how much goes down, whether mortgage insurance applies, and how long it sticks around. Rate gets all the attention. Program structure is what you actually live with.
Personalized solutions to help you buy, sell, or invest in real estate with ease.
A quick prequalification shows you what you qualify for.
We gather the documents to move your file into underwriting.
Our team evaluates the full loan package.
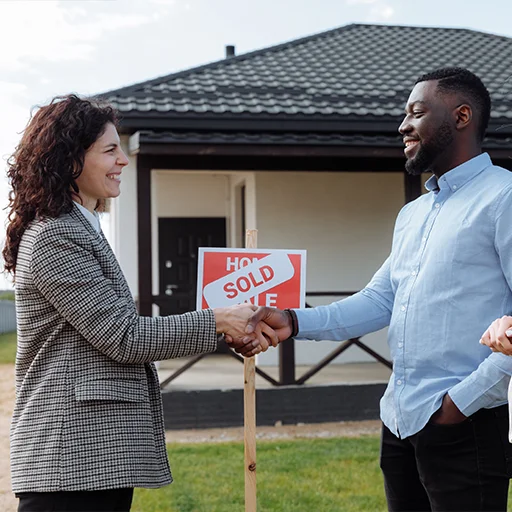
Final documents go to the title company for closing.
Five stars, more than 1,500 times. Read what people say about buying and refinancing with MVP.

 Eligio Marcoviche
Trustindex verifies that the original source of the review is Google.
Michael Guevara, professional, details on information giving me, every may of the closed out. Michael Guevara es un profesional en el work que hace., muy detallista durante el cierre de contrato. My recommendation to do business with him. Airborne all the way Michael ThibaultJosh did a good job helping me refinance would recommend to friends and family
 Wesley MJosh was great looking forward to doing this with him again in the future
 Mike GreenI want to thank Joe Soto for leading me through the refinance process! He made the process go fast and effortlessly, efficiently and most of all personally. That personal touch made all the difference in making this a great experience!
 Mario VelazquezNickolas Jamgochian was great helping me navigating the process of getting a difficult process of exiting my previous mortgage management services, and I am very thankful for the help. Nick is highly recommended
 Regina BanksGreat lower interest rate and excellent customer service! 💯💯💯
 Lawrence RaithGot everything taken care of quickly and hassle free
 Scott SeemanNick was great, hoping to use him again in six months!
We would rather you understand the loan than sign one quickly. You get one banker from application to keys, straight answers about cost, and a recommendation based on your situation instead of whatever is easiest to close.
Ready to see what you qualify for? Our short application takes a few minutes and a mortgage professional will follow up to walk you through your options.
DISCLAIMER:
This is not a commitment to lend or extend credit. All loans are subject to credit approval. Information is subject to change without notice. Other restrictions may apply. VA loan benefits are subject to eligibility requirements determined by the U.S. Department of Veterans Affairs.
More than the down payment alone. Conventional loans start at 3% down and FHA at 3.5%, while eligible veterans and service members can buy with nothing down. On top of that, budget for closing costs, which commonly run 2% to 5% of the loan amount and cover appraisal, title, origination, and prepaid taxes and insurance. Lenders also like to see some reserves left after closing. A seller may agree to cover part of the closing costs, which is worth raising with your agent.
It depends on your service history, credit, and how much you have saved. If you or your spouse served, a VA loan is usually the first thing to price out: no down payment and no monthly mortgage insurance. Otherwise it generally comes down to conventional versus FHA. Conventional tends to win when your credit is solid, because the mortgage insurance eventually falls off. FHA is more forgiving of a lower score. We compare them side by side rather than steering you to one.
Yes. VA purchase loans are part of what we do every day, and the benefit is not a one-time offer — many veterans use it more than once. You will need a Certificate of Eligibility, and a one-time funding fee applies, though it is waived for many borrowers with a service-connected disability. If you are eligible, tell us early, because it changes the math on everything else.
No. Conventional loans generally start around a 620 score, FHA can go to 580 with 3.5% down and lower with a larger down payment, and VA loans have no VA-set minimum, though individual lenders set their own. Credit is only one input — income stability, debt-to-income ratio, and the property itself all factor in. If your score is the thing holding you back, we will tell you specifically what to work on instead of just declining you.
Most purchases close in 30 to 45 days from accepted offer, and the timeline is driven as much by the appraisal, title work, and the seller as by the loan itself. The fastest way to protect your date is to get pre-approved before you shop and to send documents back quickly once you are under contract. We coordinate with your agent, the title company, and the appraiser so nothing sits waiting on us.